Fintech
Fintech Platforms Increasingly Integrate USDT as Stablecoin Payments Gain Global Adoption
Financial technology companies around the world are exploring new ways to improve digital payments and cross border transactions. One development attracting increasing attention is the integration of stablecoins into fintech platforms. Among the available stablecoins, USDT has become one of the most widely used digital dollar assets in global cryptocurrency markets. Its stability and high liquidity have encouraged fintech firms to experiment with stablecoin payments as part of broader efforts to modernize financial infrastructure. As digital commerce continues to expand internationally, fintech platforms are gradually incorporating blockchain based settlement tools into their payment ecosystems.
Stablecoins and the Evolution of Digital Payments
Stablecoins are designed to maintain a value close to traditional currencies such as the US dollar while operating on blockchain networks. This structure allows transactions to occur quickly without relying on conventional banking intermediaries. Fintech companies are particularly interested in these features because they reduce settlement times and enable faster international transfers. Traditional cross border payments can take several days to process through banking systems. Stablecoin transactions, by contrast, can often be completed within minutes. For fintech firms seeking to improve user experience and payment efficiency, this technological advantage is significant.
Growing Role of USDT in Fintech Infrastructure
USDT has emerged as a leading stablecoin in digital finance due to its widespread adoption across cryptocurrency exchanges and blockchain networks. Fintech platforms exploring stablecoin integration often begin with USDT because it already has strong liquidity and broad market acceptance. Payment applications and digital wallets are experimenting with stablecoin support that allows users to send funds globally without relying entirely on traditional banking rails. This growing integration highlights how fintech companies are gradually bridging the gap between conventional financial services and blockchain based financial infrastructure.
Cross Border Payments and Business Transactions
One of the most practical applications of stablecoins within fintech platforms involves cross border payments. Businesses engaged in international trade frequently face high transaction fees and long settlement delays when using traditional banking channels. Stablecoin payments provide an alternative that can reduce both time and cost. Freelancers, technology professionals and digital entrepreneurs have also shown interest in stablecoin based payment systems because they allow earnings from overseas clients to be transferred more efficiently. As fintech firms expand globally, the ability to facilitate rapid international transactions becomes increasingly valuable.
Financial Inclusion and Access to Global Markets
Another factor supporting the growth of stablecoin payments is financial inclusion. In many regions access to international banking services remains limited or expensive. Fintech platforms aim to address this challenge by offering digital financial tools that connect users with global payment networks. Stablecoins such as USDT allow individuals and businesses to participate in digital commerce without needing complex banking arrangements. This capability has helped stablecoins gain traction in emerging markets where digital finance solutions are expanding rapidly.
Regulatory Attention and Industry Development
The rise of stablecoin payments has also drawn attention from financial regulators. Governments and central banks are studying how digital assets interact with traditional financial systems. Key areas of focus include transparency, reserve backing and consumer protection. While regulatory frameworks continue to evolve, many fintech firms believe that clearer rules will ultimately support responsible innovation. Proper oversight can help build confidence among both users and financial institutions that stablecoin based payment systems operate within secure and transparent environments.
Fintech Innovation and Blockchain Integration
Fintech companies are increasingly experimenting with blockchain technology beyond simple cryptocurrency trading services. Developers are building payment gateways, digital wallets and decentralized finance tools that rely on blockchain networks for settlement and record keeping. Stablecoins are often central to these systems because they provide a predictable value that simplifies transactions. As fintech innovation continues to accelerate, blockchain integration is expected to become a larger component of financial technology strategies across the industry.
Outlook
The integration of USDT into fintech payment systems reflects a broader shift toward faster and more flexible digital financial infrastructure. As cross border commerce expands and digital platforms grow, stablecoins may play an increasingly important role in global payment networks.
You may like

Pakistan’s Digital Payments Hit 3.7 Billion as Raast Processes Rs23.27 Trillion

Emerging Markets Turn to USDT for Cross Border Transactions as Dollar Liquidity Tightens

Crypto Liquidity and Capital Flows: Could Rising USDT Activity Influence Pakistan’s Equity Markets

US Senators Seek Compromise to Advance Crypto Clarity Act Amid Stablecoin Debate

Data Breach Hits Fintech Lender Figure Exposing Nearly One Million Accounts

Pakistan’s Budget Debate Faces New Questions as USDT Usage Reflects Digital Dollarization Trends
Fintech
OpenAI Unveils Astra With Major Capability Claims

OpenAI has unveiled Astra, describing it as its most capable AI model yet, according to the supplied report. The model reportedly improves coding, cybersecurity, and computer and browser use. Initial access is through OpenAI’s Daybreak cybersecurity programme, with paid ChatGPT plans and API access expected to follow. OpenAI says Astra can help identify previously unknown vulnerabilities and outperform earlier models on software engineering benchmarks. However, its reported use of opaque recurrence has raised questions about reasoning transparency and oversight.
Fintech
Data Breach Hits Fintech Lender Figure Exposing Nearly One Million Accounts
A major data breach has affected fintech lender Figure Technology Solutions after hackers exposed sensitive personal information linked to nearly one million accounts. The company confirmed that details from approximately 967,200 accounts were compromised following a social engineering attack targeting an employee. The exposed data includes names, email addresses, phone numbers, home addresses, and dates of birth. Although no financial account numbers were disclosed in the initial report, cybersecurity experts warn that the leaked information could still be used for identity theft, phishing attacks, and financial fraud campaigns targeting affected users.
Social Engineering Attack Enabled Unauthorized Access
Figure Technology Solutions reported that the breach occurred when a company employee was manipulated through a social engineering attack. Instead of breaching the platform’s underlying technology systems, the attacker exploited human vulnerability by tricking the employee into providing access that allowed files to be downloaded from internal systems.
According to the company, the suspicious activity was quickly detected and the unauthorized access was blocked soon afterward. The company also confirmed that it has hired a forensic cybersecurity firm to investigate which files were accessed and determine the full extent of the incident. Figure stated that it is communicating with partners and affected users while reviewing internal security procedures to prevent similar attacks in the future.
Blockchain Lending Platform Remains Technically Secure
Figure Technology Solutions operates a fintech lending platform built on the Provenance blockchain, a system designed to support transparent and secure financial transactions. Founded in 2018, the company has become a major player in digital lending and says it has facilitated more than $22 billion in home equity transactions through partnerships with banks, credit unions, and financial technology companies.
The company emphasized that the breach did not involve a direct attack on the blockchain infrastructure itself. Instead, attackers gained access through the compromised employee account, allowing them to download files stored within internal systems. Security specialists note that incidents like this demonstrate how even platforms built on advanced technologies can still be vulnerable when attackers target human behaviour rather than the technology itself.
Cybercriminal Groups Increasingly Exploit Employee Credentials
Security researchers say the tactics used in the attack resemble methods employed by well-known hacking groups such as ShinyHunters. These groups frequently impersonate IT support personnel or company administrators and persuade employees to reveal login credentials through phishing pages or fraudulent login portals.
Once attackers obtain access to corporate single sign-on systems, they can navigate across multiple internal platforms that share the same authentication system. Because these systems allow users to access several applications with one login, attackers who gain access can potentially reach large volumes of sensitive data quickly.
Experts say this type of attack has become increasingly common as cybercriminals focus more on manipulating employees instead of attempting to break complex security systems directly.
Experts Warn Personal Data Exposure Could Fuel Fraud Attempts
Cybersecurity experts caution that the exposure of personal information in data breaches can have serious consequences even when financial data is not directly compromised. Criminals can combine leaked information with other publicly available data to launch highly targeted phishing campaigns, impersonation attempts, or identity theft schemes.
Once attackers obtain detailed personal profiles of individuals, they can craft messages that appear to come from legitimate financial institutions, government agencies, or technology platforms. These scams often attempt to convince victims to reveal additional financial details or transfer funds under false pretenses.
As digital financial services continue expanding globally, fintech companies are becoming increasingly attractive targets for cybercriminals seeking access to large volumes of customer data.
Outlook
The Figure data breach highlights a growing cybersecurity challenge across the fintech industry: advanced financial technology alone cannot eliminate risks associated with human error and social engineering. As digital finance platforms continue to scale and manage larger volumes of sensitive data, companies will need to strengthen internal security practices alongside technological protections. Experts expect fintech firms to increase investment in employee cybersecurity training, identity verification tools, and multi-factor authentication systems to reduce vulnerabilities. The incident also reinforces the importance of combining technological innovation with robust operational security as fintech services become increasingly central to global financial infrastructure.
Fintech
FinTech Startup Orca Fraud Raises $2.35 Million to Strengthen Real-Time Payment Security
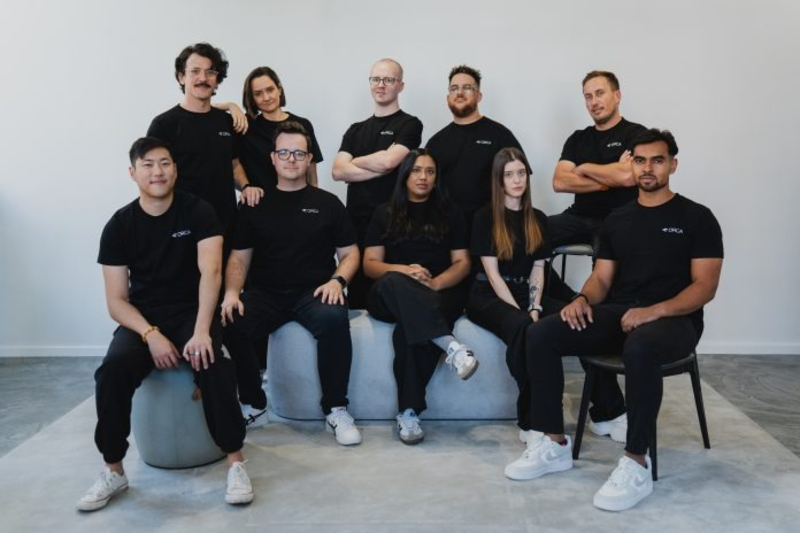
Financial technology startup Orca Fraud has secured 2.35 million dollars in new funding as it expands its fraud detection platform designed to protect digital payment ecosystems. The company plans to use the investment to enhance its real time fraud monitoring infrastructure and broaden its presence across global payment networks.
As digital payments continue to grow rapidly in emerging markets, financial institutions face increasingly sophisticated fraud threats. Payment fraud is evolving alongside new financial technologies, forcing fintech companies to develop smarter tools capable of identifying suspicious activity instantly.
Orca Fraud focuses on building technology that detects financial crime directly within payment flows rather than relying solely on traditional post transaction analysis. This approach allows the system to identify fraudulent behaviour as transactions occur, helping financial institutions respond before significant damage is done.
Emerging Markets Present Unique Fraud Detection Challenges
Fraud detection in digital finance is particularly challenging in emerging markets where financial systems are evolving rapidly. Traditional fraud prevention technologies were originally designed for more structured banking environments with consistent datasets and predictable user behaviour.
In many developing economies, financial ecosystems include a mix of mobile wallets, agent banking networks, digital payment platforms, and informal economic activities. These environments generate complex transaction patterns that can make fraud detection more difficult.
Legacy fraud monitoring systems typically rely on static identity checks performed when users first open accounts. Once customers are onboarded, these systems track a limited set of identifiers to detect suspicious activity.
However this model is becoming less effective as digital finance expands. Fraud networks increasingly exploit gaps between different payment systems, moving funds across multiple channels before detection systems can react.
The rapid growth of mobile financial services has also accelerated transaction speeds, reducing the time available for traditional monitoring systems to identify threats.
Orca’s Technology Monitors Transactions Across Multiple Payment Channels
Orca Fraud has developed a technology platform that monitors financial activity across multiple payment rails simultaneously. Instead of examining transactions only after they are completed, the system embeds machine learning intelligence directly into the payment flow.
This allows the platform to analyze behavioural patterns, transaction signals, and cross platform activity in real time. When suspicious behaviour is detected, the system can alert financial institutions or trigger automated security responses.
Multi channel monitoring has become increasingly important as digital financial ecosystems diversify. For example, a fraudulent scheme may begin with a mobile wallet transaction before quickly moving funds through bank transfers, card payments, or cryptocurrency exchanges.
Traditional fraud detection systems that monitor only one payment channel may fail to recognize these patterns early enough to prevent losses.
Orca’s platform attempts to address this issue by aggregating transaction data across different payment networks. By analyzing signals from multiple channels simultaneously, the system can detect complex fraud patterns that span several financial services.
Machine Learning Models Adapt to Regional Payment Behaviour
Another key feature of the Orca platform is its use of machine learning models trained on region specific financial data. Payment behaviour can vary significantly across different markets, particularly in regions where digital finance is developing quickly.
Many fraud detection tools rely on datasets built primarily from Western banking systems. These datasets may not accurately reflect the transaction patterns seen in emerging markets where mobile payments and informal economic activity are more common.
Orca’s system collects and analyzes payment data from multiple markets to build detection models tailored to regional financial environments. As the platform expands into new markets, transaction signals identified in one region can help improve fraud detection in another.
This cross market intelligence allows the system to adapt to evolving fraud tactics and strengthen detection capabilities over time.
Funding Will Support Infrastructure and Global Expansion
The newly raised funding will help Orca Fraud expand its technical infrastructure and improve the performance of its fraud detection platform. As payment networks process increasing transaction volumes, fraud monitoring systems must operate at high speed while maintaining low latency.
Financial institutions require fraud detection platforms capable of handling large transaction flows without disrupting payment processing. Real time analysis must occur within milliseconds to ensure suspicious transactions are identified quickly.
Orca plans to use the investment to enhance its enterprise grade architecture and scale its machine learning capabilities to support high volume financial environments.
The company is also focusing on expanding its partnerships with payment networks, financial institutions, and fintech platforms across emerging markets.
Outlook
As digital financial services continue expanding globally, fraud prevention technology will play a critical role in maintaining trust within payment ecosystems. Companies like Orca Fraud are developing next generation detection systems designed to monitor financial activity in real time and respond quickly to increasingly complex fraud threats.


Trending
 Artificial Intelligence4 months ago
South Korea Unveils $880 Billion AI and c Investment Plan
 Football3 months ago
Better Future Pakistan | Match -1 | Norway
- Latest News7 months ago
Crypto Liquidity and Capital Flows: Could Rising USDT Activity Influence Pakistan’s Equity Markets
 Latest News7 months ago
Etihad Town Phase I Introduces Overseas Block with Residential and Commercial Plot Opportunities in Lahore
 Football3 months ago
Better Future Pakistan | LIVE Match | Norway
 Latest News7 months ago
From Catalog Clicks to Conversational AI: How Moeed Sheikh Is Building Revenue Driven Digital Experiences
 Latest News7 months ago
Punjab Introduces Mandatory Underground Infrastructure Rules for New Housing Societies in Lahore
 Latest News7 months ago
PSX Bloodbath as KSE100 Plunges Over 13,000 Points After Trading Resumes