Connect with us

IMF & Global Finance

IMF Delegation Meets OICCI in Karachi
The Overseas Investors Chamber of Commerce and Industry (OICCI) urged Pakistan to expand taxation into under-taxed sectors and reduce regulatory and compliance burdens during a meeting with an International Monetary Fund (IMF) delegation in Karachi. Representing foreign investors, OICCI also called for stronger investor protection and clearer coordination between federal and provincial authorities. The chamber said Pakistan should use gains from macroeconomic stabilization to accelerate private investment, exports, energy security and structural reforms. The IMF delegation met OICCI leaders and representatives of member multinational companies.

Share on:
Continue Reading
Click to comment

Leave a Reply

Your email address will not be published. Required fields are marked *

IMF & Global Finance

IMF Calls for Cooperation in Bangkok
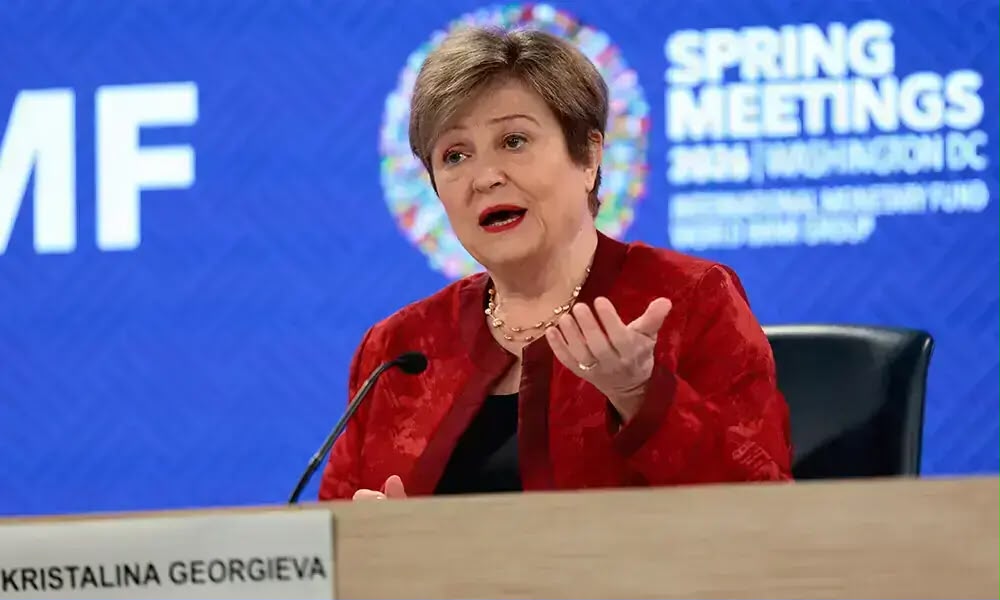
IMF Managing Director Kristalina Georgieva has urged global financial leaders to strengthen international cooperation as the world economy faces rising debt, rapid advances in artificial intelligence and a surge in cyberattacks. Speaking at the IMF–World Bank Annual Meetings in Bangkok on Friday, she called for urgent, practical action to address these growing risks.

Share on:
Continue Reading

IMF & Global Finance

Pakistan Discusses Rating Path with Fitch
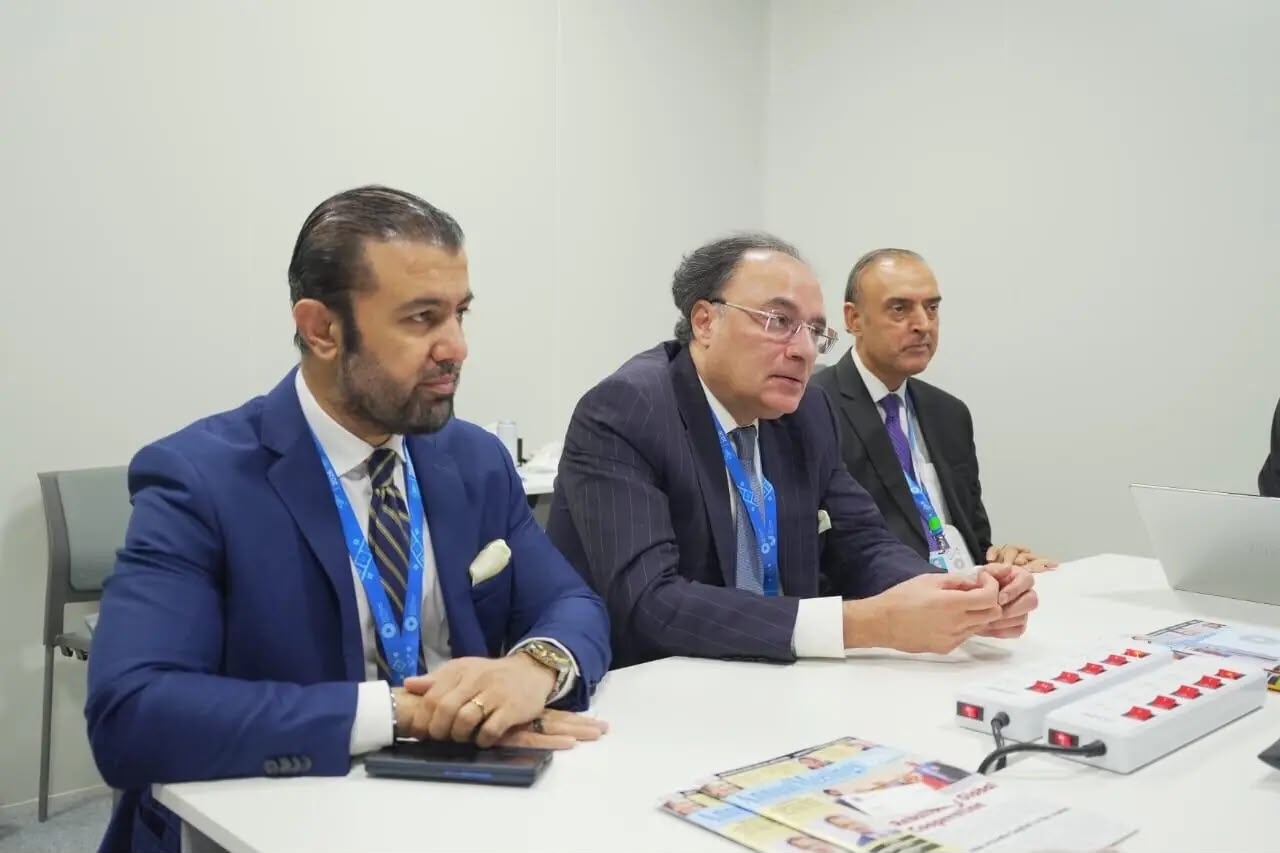
Pakistan has sought Fitch Ratings’ assessment of the steps required to advance towards the BB sovereign rating category. Finance Minister Muhammad Aurangzeb and the Governor of the State Bank of Pakistan discussed the country’s economic performance and sovereign credit outlook with Fitch representatives in Bangkok. The meeting took place on the sidelines of the 2026 World Bank Group–IMF Annual Meetings. Fitch’s assessment could help clarify the economic and policy requirements Pakistan needs to meet to strengthen its credit profile.

Share on:
Continue Reading

IMF & Global Finance

Digital Fraud Threatens Pakistan’s Economy
Pakistan’s estimated losses from cyber-enabled financial fraud amount to 2.5% of GDP, well above the global average of 0.45%, according to an IMF and World Bank report. Bangkok Blueprint in Action, developed in coordination with the Bank of Thailand, outlines a framework to help countries prevent, detect and address fraud in digital financial services. The report says Asia has the highest fraud losses globally, led by Pakistan at 2.5% of GDP, followed by Malaysia at 2.1% and India at 1.3%. The figures underline growing risks to Pakistan’s digital economy as fraudsters target online platforms, telecom networks and payment systems.

Share on:
Continue Reading

Trending